Baillie Gifford Shin Nippon
Launched in 1985, the Baillie Gifford Shin Nippon trust aims to provide long-term capital growth by investing in smaller companies listed on the Japanese stock market. Shin Nippon means ‘new Japan’ and this trust focuses on emerging or disrupted sectors, where the manager sees innovative growth opportunities. The team are prepared to bide their time while these companies reach their full potential and, while the trust can be highly volatile, patient investors have been richly rewarded.

Quick Access
Our Opinion
The quality of Baillie Gifford’s in-house research and its specialist Japan equity team are two factors hugely in this trust’s favour. The team delves into the small-cap area of the market, where less well-researched companies can provide ample opportunity to uncover overlooked future market leaders. The trust has a strong growth style bias, investing in companies with above-average capital-growth prospects with a five-year view.
The trust has been through an incredibly tough period, reflecting the prolonged challenges faced by growth and smaller companies. Brian Lum’s appointment as lead manager in 2025 has seen the investment process refined, with greater focus on portfolio construction, position sizing and resilience alongside growth. Performance has also shown signs of improvement over the past 12 months, providing encouragement that these changes are beginning to bear fruit.
Fund Managers

Brian Lum, Lead Manager
Brian Lum is lead manager of the Shin Nippon Investment Trust and co-manager of the Japanese Smaller Companies Strategy. Brian joined Baillie Gifford in 2006. He is a CFA Charterholder and graduated with an MSci and BA (Hons) in Physics from the University of Cambridge in 2006.
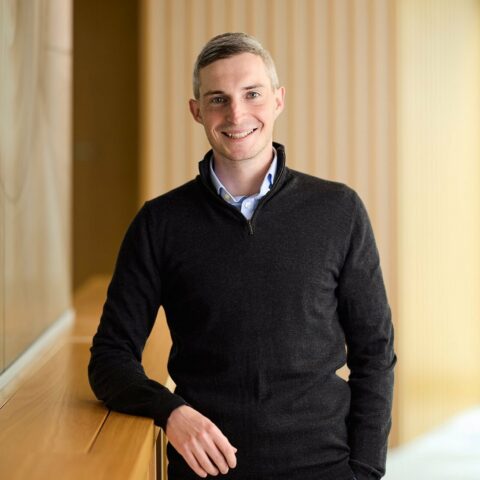
Jared Anderson, Deputy Manager
Jared Anderson is the deputy portfolio manager for the Bailie Gifford Shin Nippon Trust. Prior to joining the team, he worked in the Global Alpha, UK Equities and Fixed Income teams. Before he joined Baillie Gifford he spent two years as an Assistant Economist at the Scottish Government. Jared graduated MA (Hons) in Economics from the University of Edinburgh in 2012.
Risk

Praveen and the team play close attention to risk. For example, they reduce stock-specific risk by having a suitably diversified portfolio. Nevertheless, the trust is managed with little or no attention to the benchmark (MSCI Japan Small Cap Index). This is demonstrated by its active share. Holdings are limited to 5% of total assets at the time of purchase. If a position exceeds this size, it is monitored closely.
As with any small-cap portfolio, investors must be prepared for volatility. Likewise, small-caps can become difficult to trade during times of market stress or when growth-style investing falls out of favour. Currency fluctuation is another risk that investors need to consider.
Company Description

Founded in 1908 and employee-owned, Baillie Gifford is based in Edinburgh but has offices in London and New York. Awarded the Elite Provider for Equities Rating each year from 2015 to 2021, it specialises globally in equities, fixed income and multi-asset portfolios. The firm is owned by its senior executives and operates as a partnership.
Talking Factsheet
 Baillie Gifford Shin Nippon
Sarah Clark
Investment process
The team has an investment universe of around 2,000 companies to choose from. Idea generation is unconstrained - drawing insights from a wide network of sources - from management teams and academics to private company founders and unconventional thinkers. The team starts by adopting its five-point research framework (RADAR) for analysing both current and potential holdings.
These are:
Opportunity – What is the nature and size of the company’s addressable market over the next five to 10 years?
Edge – Can the company build a strong and sustainable competitive advantage?
Scalability – Where are the company’s financial characteristics as it grows and are there key growth bottlenecks?
Alignment – Are the management and stakeholders aligned with long-term success?
Sustainability – How do the company’s activities impact the broader society?
Each of these factors is analysed with every investment, creating a company score across these dimensions – this allows the managers to evaluate what success might look like and where their insights differ from the wider market.
Any additions are based on a combination of the research, open discussion among the team and conviction in the case. The final decision rests with the portfolio managers – the team will only buy when they believe there is a strong possibility of a company doubling its market-cap over five years and where the risk/reward is firmly in their favour.
Some of the other recent refinements of the investment process include widening the investment universe to include companies with a market-cap in excess of ¥150bn and giving the team greater flexibility to capture attractive growth opportunities as companies mature. Part of this has seen the introduction of four different growth buckets for companies.
These are:
Emerging Prospects – early-stage or loss-making businesses with significant upside but high uncertainty.
Rapid Scalers – companies with proven products and scalable models, growing rapidly into large addressable markets.
Cyclical Gainers – structurally growing industries with cyclical characteristics where strong operators can compound through downcycles.
Proven Winners – established leaders with durable advantages and long runways of compounding growth.
Risk
Praveen and the team play close attention to risk. For example, they reduce stock-specific risk by having a suitably diversified portfolio. Nevertheless, the trust is managed with little or no attention to the benchmark (MSCI Japan Small Cap Index). This is demonstrated by its active share. Holdings are limited to 5% of total assets at the time of purchase. If a position exceeds this size, it is monitored closely.
As with any small-cap portfolio, investors must be prepared for volatility. Likewise, small-caps can become difficult to trade during times of market stress or when growth-style investing falls out of favour. Currency fluctuation is another risk that investors need to consider.
ESG
The team takes a long-term approach, looking for growth opportunities with firms that are likely to be future leaders. The team believes that this long-term approach incorporates a natural bias towards sustainable business models, however this is not a formal policy of the philosophy or process. Material ESG issues that are identified in the analysis will be considered as possible reasons to not invest, but this will be on a case-by-case basis, rather than a systematic approach. There is a strong focus on governance though, with the team having regular engagement with the management of companies already held in the fund and those of prospective holdings. This is especially important when considering the smaller size of many of the companies held.
Gearing
The board has stated that, although the trust could have maximum equity gearing of 50%, it would seek to limit equity gearing to 30% at the time of drawdown.
Related Insights
Sell in May? Not this year…
When a discount isn’t just a bargain

Autumn 2025: the funds gaining and losing their Elite Ratings
The information, data, analyses, and opinions contained herein (1) include the proprietary information of FundCalibre, (2) may not be copied or redistributed without prior permission, (3) do not constitute investment advice offered by FundCalibre, (4) are provided solely for informational purposes and therefore are not an offer to buy or sell a fund, and (5) are not warranted to be correct, complete, or accurate. FundCalibre shall not be responsible for any trading decisions, damages, or other losses resulting from, or related to, this information, data, analyses, or opinions or their use. The Elite Fund rating is subjective in nature and reflects FundCalibre’s current expectations of future events/behaviour as they relate to a particular fund. Because such events/behaviour may turn out to be different than expected, FundCalibre does not guarantee that a fund will perform in line with its FundCalibre benchmark. Likewise, the Elite Fund rating should not be seen as any sort of guarantee or assessment of the creditworthiness of a fund nor of its underlying securities and should not be used as the sole basis for making any investment decision. FundCalibre disclaims any responsibility for trading decisions, damages or other losses resulting from any use of the Elite Fund rating. All performance data, as well as fund size, OCF, AMC, annual income (historic), share price discount or premium, is sourced directly from FE Analytics, and will change periodically.